
Call us: 479-935-1817
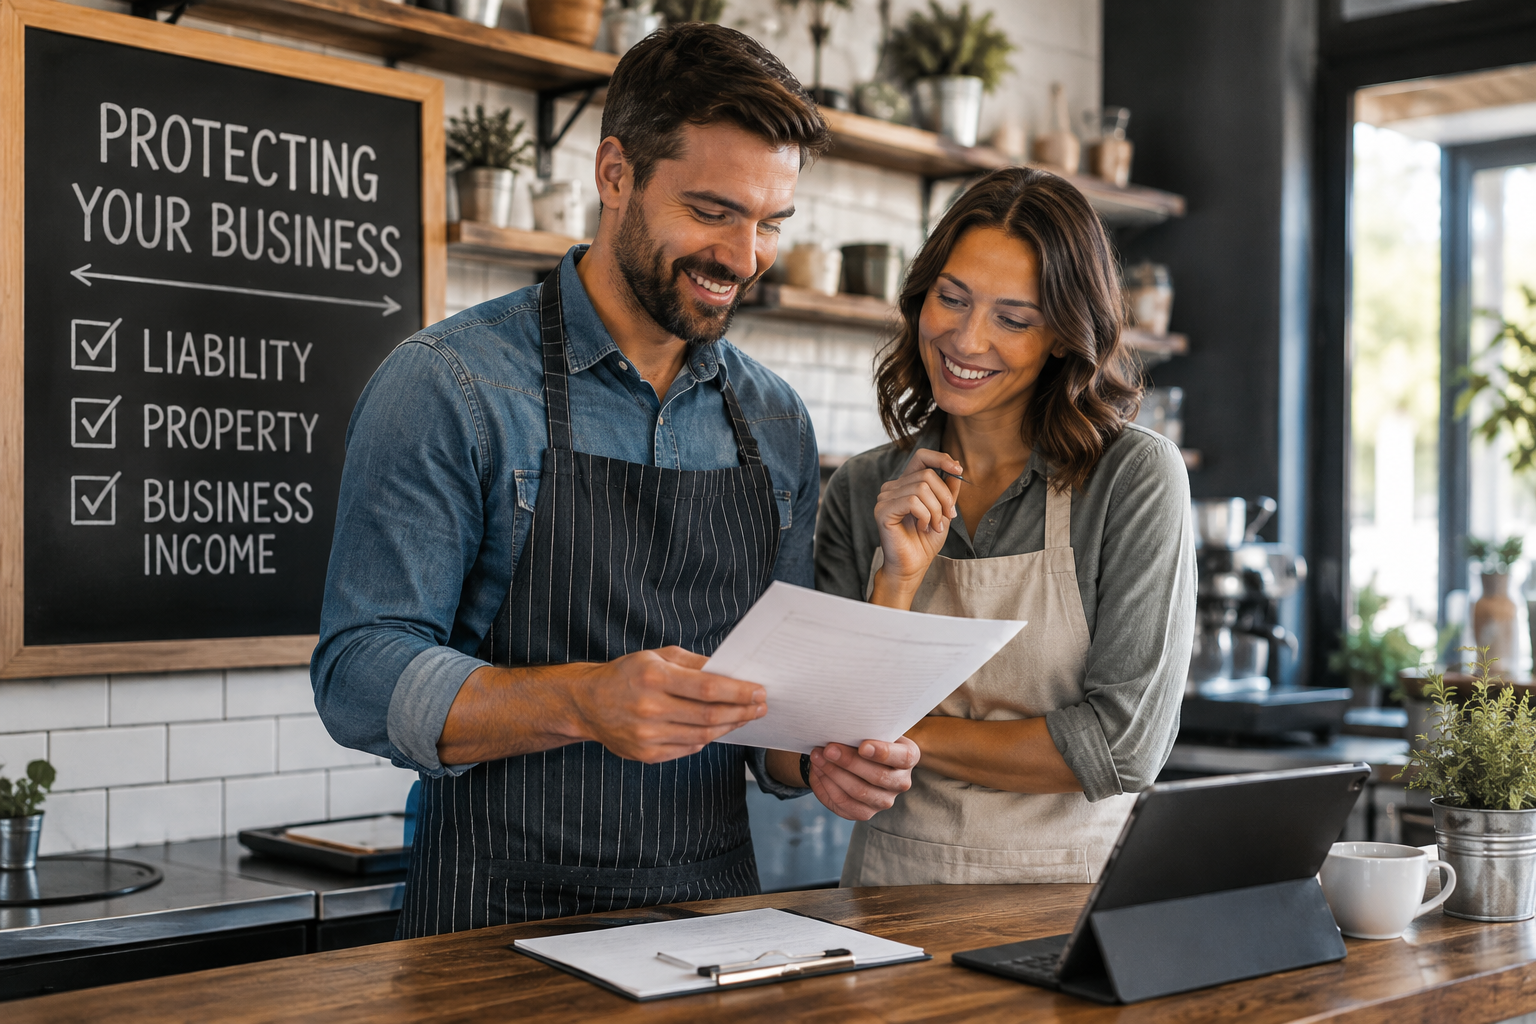

Running a small business comes with risks you cannot always predict.
A customer could slip and fall in your store. A fire could damage your equipment and inventory. A severe storm could force your business to close temporarily while repairs are completed.
Any of these situations could create significant financial pressure.
A Business Owners Policy (BOP) can help eligible small businesses protect against several common risks by combining important insurance coverages into one policy.
But what exactly does a BOP cover, and is it enough to protect your business?
At My Neighborhood Insurance in Farmington, AR, we help small business owners throughout Northwest Arkansas compare business insurance options from multiple carriers and understand how a BOP may fit their operations.
Quick Answer: What Does a Business Owners Policy Cover?
A Business Owners Policy typically combines three important types of business insurance:
- General Liability Insurance: Helps protect against certain third-party bodily injury, property damage, and personal or advertising injury claims.
- Commercial Property Insurance: Helps protect covered business buildings, equipment, inventory, furniture, and other business property against covered losses.
- Business Income Coverage: May help replace lost income and cover certain continuing expenses if a covered property loss interrupts business operations.
These coverages provide a useful foundation for many small businesses.
However, a BOP does not automatically cover every risk your business faces.
Commercial auto, workers’ compensation, professional liability, cyber liability, and other specialized coverages may require additional policies or endorsements.
What Is a Business Owners Policy?
A Business Owners Policy, commonly called a BOP, is a commercial insurance package designed for eligible small and midsize businesses.
Instead of purchasing general liability and commercial property insurance through completely separate policies, qualifying businesses may be able to combine these protections into one convenient package.
Many BOPs also include business income coverage.
Potential advantages include:
- Combining multiple coverages into one policy
- Simplifying insurance management
- Potentially reducing costs compared with separate policies
- Providing coverage options designed for small businesses
- Allowing certain additional endorsements to be added
However, not every business qualifies for a BOP.
Eligibility, available coverage, limits, and pricing depend on the insurance carrier and the nature of your operations.
1. General Liability Insurance: Protection Against Certain Third-Party Claims
General liability insurance is one of the most important components of a Business Owners Policy.
It helps protect your business from certain claims involving bodily injury, property damage, and personal or advertising injury.
Customer Injuries
Imagine a customer slips on a wet floor inside your retail store and suffers an injury.
If your business is held legally responsible, general liability coverage may help with covered medical expenses, legal defense costs, and damages, subject to policy terms and limits.
Damage to Someone Else’s Property
Suppose an employee accidentally damages a customer’s property while performing covered business operations.
General liability insurance may help address certain resulting property damage claims.
Personal and Advertising Injury
General liability coverage may also provide protection against certain personal and advertising injury claims, such as covered allegations of libel, slander, or copyright infringement in advertising.
However, general liability does not cover every type of lawsuit.
For example, professional mistakes, employee injuries, and certain employment-related claims generally require different protection.
2. Commercial Property Insurance: Protecting Your Business Assets
Commercial property coverage is another key part of a BOP.
Depending on the policy, it can help protect your business’s physical property against covered causes of loss.
This may include:
- Buildings owned by the business and insured under the policy
- Office furniture
- Computers and electronics
- Business equipment
- Inventory
- Shelving and displays
- Supplies
- Certain improvements made to rented commercial space
For example, imagine a fire damages a small retail store in Fayetteville.
If the loss is covered, commercial property insurance may help pay to repair or replace damaged property, subject to the policy’s limits, valuation provisions, and deductible.
However, coverage depends on the cause of the damage and the specific property insured.
Not every type of property damage is automatically covered.
Flooding, earthquakes, wear and tear, deterioration, and certain other causes of loss may be excluded or require additional coverage.
Replacement Cost vs. Actual Cash Value
When reviewing commercial property coverage, it is important to understand how damaged property will be valued.
Replacement cost coverage generally focuses on the cost of replacing covered property with new property of similar kind and quality, subject to policy terms.
Actual cash value generally accounts for depreciation.
That distinction can make a significant difference when replacing expensive business equipment, furniture, or inventory after a covered loss.
For a general explanation of these insurance valuation methods, read our guide to Replacement Cost vs. Actual Cash Value.
Commercial property policies can have different valuation provisions, so review the specific terms of your business policy.
3. Business Income Coverage: What Happens If Your Business Must Close?
Property damage can create costs beyond repairing a building or replacing equipment.
What happens if your business cannot operate while repairs are being completed?
That is where Business Income Coverage, also called business interruption insurance, can become especially important.
Many Business Owners Policies include this type of protection.
If a covered property loss forces your business to suspend operations, business income coverage may help replace certain lost income and pay qualifying continuing expenses.
Depending on the policy, these expenses may include:
- Lost net income
- Certain employee payroll expenses
- Rent or lease payments
- Certain loan payments
- Other eligible continuing operating expenses
Some policies also provide Extra Expense Coverage, which may help pay certain additional costs necessary to resume or continue operations.
For example, a business may need to temporarily relocate after a covered fire.
Extra Expense Coverage may help with qualifying costs of operating from another location.
Does Business Income Coverage Apply to Every Closure?
No.
Business income coverage generally requires a qualifying interruption caused by covered physical loss or damage.
Simply losing customers, experiencing a slow business period, or voluntarily closing does not automatically trigger coverage.
Policies may also include:
- Waiting periods
- Time limitations
- A defined period of restoration
- Coverage limits
- Specific exclusions
- Additional conditions for certain types of interruptions
Business owners should review these details before a loss occurs.
A Realistic Example: How a BOP Could Protect a Small Business
Imagine you operate a retail store in Farmington, Arkansas.
One evening, a covered electrical fire damages part of your building, destroys inventory, and forces the store to close temporarily.
Depending on the policy, different components of your BOP may apply.
Commercial Property Coverage
May help pay to repair the covered building damage and replace damaged inventory, equipment, or furniture.
Business Income Coverage
May help replace qualifying lost income and cover certain continuing expenses while operations are suspended because of the covered property loss.
Extra Expense Coverage
May help with eligible additional costs, such as temporarily relocating your business to another location.
Now imagine a customer also files a covered bodily injury claim against your business in an unrelated incident.
General liability coverage may help address that claim.
This example illustrates why combining property, liability, and business income coverage can be valuable for many small businesses.
Actual claim payments depend on the specific policy, cause of loss, limits, exclusions, and conditions.
What Does a Business Owners Policy Not Automatically Cover?
One of the biggest misconceptions about commercial insurance is that purchasing a BOP means your business is fully protected.
That is not necessarily true.
A BOP can provide a strong insurance foundation, but some business risks generally require separate policies or additional endorsements.
Commercial Auto Insurance
If your company owns vehicles, uses work trucks, makes deliveries, or has employees regularly driving for business purposes, commercial auto insurance may be necessary.
Standard BOP liability coverage generally does not replace commercial auto insurance.
Business owners should also avoid assuming that personal auto insurance covers every type of business vehicle use.
The correct coverage depends on vehicle ownership, use, drivers, and underwriting requirements.
Workers’ Compensation Insurance
Workers’ compensation insurance generally provides benefits for qualifying work-related injuries or illnesses.
It is not automatically included in a standard BOP.
Arkansas generally requires most employers with three or more employees to carry workers’ compensation insurance.
However, exceptions and additional requirements apply. Certain construction and subcontracting arrangements may require coverage with fewer employees.
Employers should verify their obligations rather than assuming their business is exempt.
Professional Liability Insurance
Professional liability insurance, also called Errors and Omissions Insurance or E&O, helps protect against certain claims involving professional mistakes, negligence, or failures in providing covered professional services.
This may be especially important for:
- Consultants
- Accountants
- Technology companies
- Design professionals
- Professional service providers
- Other businesses offering specialized advice or expertise
General liability insurance generally does not replace professional liability coverage.
Cyber Liability Insurance
Cyber liability insurance can help address certain financial losses resulting from cyber incidents, data breaches, ransomware, and other covered digital risks.
A standard BOP does not necessarily include comprehensive cyber protection.
Businesses that store customer information, process online payments, or rely on digital systems should review available cyber insurance options.
Employment Practices Liability Insurance
Employment Practices Liability Insurance, commonly called EPLI, can help protect against certain employment-related claims.
These may involve allegations of wrongful termination, discrimination, harassment, or other covered employment practices.
EPLI is not typically included automatically in a standard BOP.
Commercial Umbrella Insurance
Commercial umbrella or excess liability insurance may provide additional liability limits above certain underlying policies.
For businesses with significant liability exposure, standard BOP limits may not provide enough protection for every possible claim.
Flood Insurance
Flooding is another important concern.
Standard commercial property insurance generally excludes flood damage.
Businesses that need flood protection may have to purchase separate flood insurance or specialized coverage.
Having a BOP does not automatically mean flood damage to your building, equipment, or inventory is covered.
Does Every Arkansas Small Business Qualify for a BOP?
No.
Business Owners Policies are generally designed for businesses that meet certain eligibility requirements.
Insurance companies evaluate factors such as:
- Business industry
- Type of operations
- Annual revenue
- Payroll
- Number of employees
- Business location
- Building size and characteristics
- Property values
- Claims history
- Liability exposures
- Other underwriting considerations
A small retail store may have different insurance needs from a construction company, restaurant, professional office, or property management business.
Some businesses may qualify for a BOP with additional endorsements.
Others may require separate commercial policies or a more customized commercial package.
The best approach is to review how the business actually operates before selecting coverage.
What Types of Businesses May Benefit From a BOP?
A BOP may be a practical option for many eligible businesses, including:
Retail Stores and Boutiques
May benefit from general liability, inventory protection, business property coverage, and business income coverage.
Professional Offices
May need protection for office equipment, furniture, premises liability, and business interruption. Separate professional liability or cyber coverage may also be important.
Small Service Businesses
May benefit from property and liability coverage, depending on the work performed and eligibility requirements.
Restaurants and Food Service Businesses
May need property, liability, and business income protection, along with additional coverage for equipment breakdown, food spoilage, liquor liability, or other specialized risks.
Contractors and Trade Businesses
Some contractors may qualify for BOP options, while others need customized coverage involving tools, equipment, jobsite liability, vehicles, workers’ compensation, and other risks.
Property Managers and Property Owners
Certain property management operations may qualify for business insurance packages, but rental property and commercial building ownership can require more specialized coverage.
If you own residential rental properties, our Landlord Insurance page explains coverage considerations specific to rental property owners.
Is a Business Owners Policy the Same as General Liability Insurance?
No.
General liability insurance is one type of business insurance.
A BOP is a broader insurance package that typically includes general liability, commercial property, and business income coverage.
For example, a small business may purchase standalone general liability insurance to address certain third-party injury and property damage claims.
However, general liability alone generally does not pay to replace the business’s own damaged equipment or inventory after a fire.
Commercial property insurance addresses different risks.
A BOP combines these types of protection into one package for eligible businesses.
A business that only purchases general liability insurance should not assume it also has commercial property or business income coverage.
How Much Does a Business Owners Policy Cost in Arkansas?
BOP premiums vary depending on the business and the insurance carrier.
Factors that can affect the cost include:
- Industry and business operations
- Annual revenue
- Payroll
- Business location
- Building construction and condition
- Property and equipment values
- Claims history
- Liability limits
- Property deductibles
- Optional endorsements
A small office with limited equipment may have very different insurance costs from a retail business with significant inventory or a restaurant with specialized equipment.
Bundling common coverages through a BOP may be cost-effective, but that does not guarantee it will always be less expensive than separate policies.
Comparing both the premium and coverage is important.
What Should You Review Before Buying a BOP?
Before selecting a Business Owners Policy, make sure you understand what is included.
Important questions include:
- What general liability limits does the policy provide?
- What business property is covered?
- Is the building insured, or only its contents?
- Are inventory and equipment values accurate?
- Is property covered at replacement cost or actual cash value?
- Does the policy include business income coverage?
- What waiting periods or time limitations apply?
- Are there separate deductibles for certain losses?
- What optional endorsements are available?
- Does your business require additional commercial auto, workers’ compensation, professional liability, or cyber coverage?
- Does the policy meet your lease or contract requirements?
You should also review your coverage when your business grows, hires employees, purchases expensive equipment, expands into new services, or changes locations.
Existing clients can request policy changes or insurance documents through our Service Center.
Why Work With an Independent Insurance Agency?
Choosing a Business Owners Policy should involve more than finding the lowest premium.
Different insurance carriers may offer different eligibility requirements, property limits, liability limits, deductibles, and endorsements.
At My Neighborhood Insurance, we work with multiple commercial insurance carriers to help Arkansas business owners compare available options.
We take the time to understand:
- What your business does
- Where you operate
- Whether customers visit your location
- What equipment and property you own
- Whether you have employees
- Whether you operate business vehicles
- What contracts or leases require
- What risks may not be addressed by a standard BOP
We help businesses throughout Farmington, Fayetteville, Prairie Grove, Lincoln, Greenland, West Fork, and surrounding Northwest Arkansas communities.
Whether you are opening a new business or reviewing an existing policy, we can help you evaluate whether a BOP or a more customized commercial insurance package makes sense.
Frequently Asked Questions About Business Owners Policies
What does a BOP cover in Arkansas?
A Business Owners Policy typically combines general liability, commercial property, and business income coverage for eligible businesses. It may also offer optional endorsements. Exact coverage depends on the insurer and policy.
Does a BOP include workers’ compensation insurance?
No, standard BOPs generally do not include workers’ compensation. Arkansas employers may be required to obtain separate workers’ compensation insurance depending on employee count, industry, and other legal requirements.
Does a BOP include commercial auto insurance?
No, commercial auto coverage is generally separate from a standard BOP. Businesses that own vehicles or use vehicles for commercial activities should review whether commercial auto or hired and non-owned auto liability coverage is appropriate.
Is a BOP the same as general liability insurance?
No. General liability is one component of a BOP. A Business Owners Policy typically combines general liability with commercial property and business income coverage.
Does business interruption insurance cover every temporary closure?
No. Business income coverage generally requires a qualifying interruption resulting from covered property damage. Waiting periods, restoration periods, limits, and exclusions may apply.
Can a small business get a BOP without owning its building?
Potentially. Eligible businesses that lease their premises may obtain BOP coverage for business personal property, general liability, and business income. The policy should reflect the lease arrangement and the property the business is responsible for insuring.
Is a BOP required by Arkansas law?
Arkansas does not generally require every small business to purchase a BOP. However, particular types of insurance may be legally required depending on the business, and landlords, lenders, customers, or contracts may establish additional insurance requirements.
Protect Your Arkansas Business With the Right Insurance
A Business Owners Policy can be an excellent starting point for protecting an eligible small business.
By combining general liability, commercial property, and business income coverage, a BOP can help address several common risks in one convenient package.
However, your business may need additional protection depending on your industry, employees, vehicles, property, and daily operations.
Not sure whether a BOP provides enough coverage for your business?
My Neighborhood Insurance can help you review your risks, compare available policies from multiple carriers, and understand what protection fits your operations.
Call us at 479-935-1817 or request a Business Owners Policy quote to explore your commercial insurance options.
You can also contact My Neighborhood Insurance in Farmington, AR to schedule a business insurance review.
We will help you understand your options and find insurance coverage that supports the business you have worked hard to build.